Back to articles
The Difference Between Debit and Credit Cards
Credit and debit cards can both be used to make purchases, but they work in very different ways. A debit card draws directly from the money in your checking account, while a credit card lets you borrow money from a lender and repay it later.
The right choice can depend on your financial situation and what you are using the card for. This guide covers how each card works, how they compare, and what to consider when deciding which one to use.
Key points
- A debit card draws directly from your checking account, while a credit card lets you borrow money and repay it later, meaning interest can apply if you do not clear your balance each month.
- Using a credit card responsibly can help you build a good credit history, while debit card use is not reported to the credit bureaus and has no direct impact on your credit.
- Credit cards carry stronger legal protections against fraud and unauthorised charges, while with a debit card your liability typically depends on how quickly you report a problem.
Credit card vs. debit card
A debit card is linked directly to your checking account, and how much you can spend is limited by your account balance. You can likely use as much or as little of your available funds as you want. A credit card is not linked to your checking account. You don’t pay anything upfront, and how much you can spend is dictated by your credit limit minus your existing balance.
What is credit?
Credit is the ability to make purchases now using a lender’s funds with the agreement to repay the lender at a later date.
Revolving credit gives you a set credit limit that you can borrow against repeatedly, up to that limit, as long as you continue to make payments and your account remains in good standing. Most credit cards and branded store cards fall into this category. Instead of making a fixed payment, you have to pay the credit card company a minimum amount each month based on your outstanding balance. As long as you have available credit, you can continue to borrow until you reach your credit limit.
Installment credit allows you to borrow a sum of money and pay it back in a series of fixed payments, at a specific interest rate, over a specific period of time. Traditional car loans and mortgages are two examples.
By using your credit card responsibly and making your monthly payments on time, you can build a strong credit history and improve your credit score. The two biggest factors in your credit score, as calculated by FICO®, are your payment history (consistently making payments on time) and your credit utilization ratio (the total balance as a percentage of your combined credit limit on all your cards). Together, these two things account for 65% of your FICO® score (35% and 30% respectively). [1]
What is debit?
A debit card is a payment card linked to a checking or savings account that lets you make purchases, withdraw cash, and pay bills using money you already have. There is little debt risk from using the card itself, though if your bank offers overdraft coverage, transactions that exceed your balance may still be processed and result in an overdraft fee. [2]
Debit cards can be more convenient and secure than cash and are widely accepted by merchants. You can also use a debit card to withdraw cash from an ATM. Unlike an ATM-only card, which is limited to ATM transactions, a debit card can also be used to make purchases in store and online.
It's worth noting that prepaid debit cards work differently. They are loaded with funds in advance and are not linked to a checking account. Both work for purchases, but It's worth noting that prepaid debit cards work differently. They are loaded with funds in advance and are not linked to a checking account. Unlike standard debit cards, they may carry more fees.
Because debit card transactions draw directly from your bank account, you will not typically face the interest charges or billing statements you would expect with a credit card. However, costs can still apply. Using an out-of-network ATM can result in fees from both your bank and the ATM operator, often between $1.50 and $5 per transaction. [2]
The main differences between debit and credit
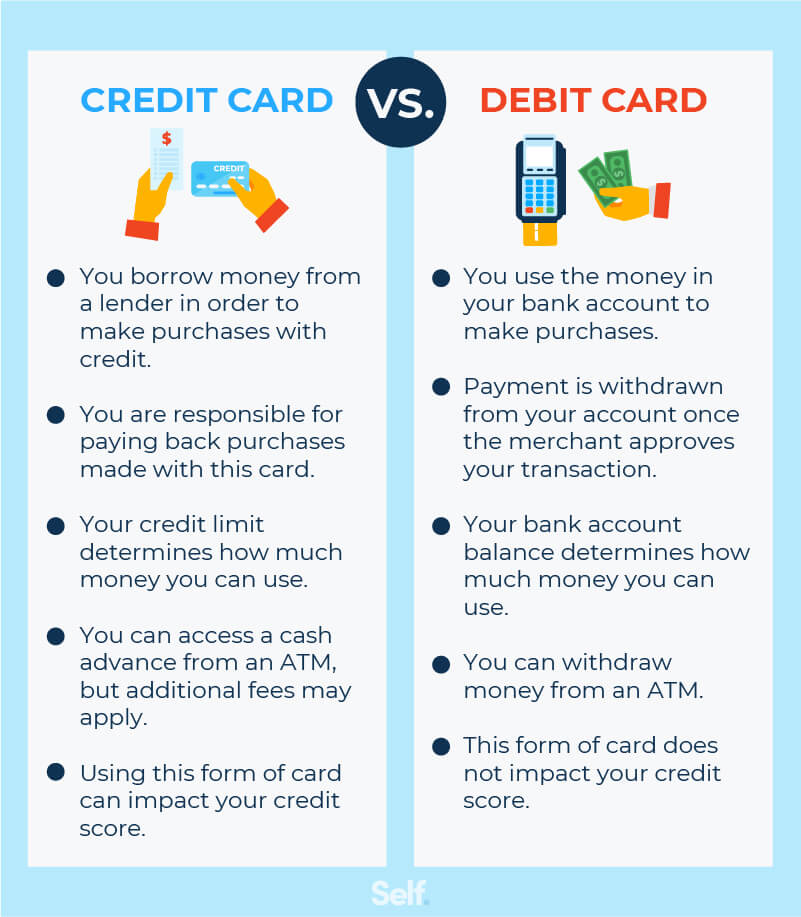
While both card types can be used to make purchases in stores and online, they work in fundamentally different ways. A debit card draws directly from the money in your checking or savings account, meaning you are not borrowing money and will not pay interest. A credit card allows you to borrow money to make a purchase and repay it later, and how you manage that repayment can affect your credit history.[3]
|
Credit Cards vs Debit Cards |
||
|---|---|---|
|
Feature |
Credit card |
Debit card |
|
Purpose |
Borrow money for purchases now and repay it later |
Pay with money already in your checking or savings account |
|
Spending limit |
The maximum amount you are allowed to borrow on the card |
Limited to your checking or savings account balance/available funds |
|
Credit impact |
Can help build a good credit history if you pay on time |
Typically does not help build credit history; not usually reported to credit bureaus |
|
Interest |
Charged on unpaid balance carried month to month |
No interest charged because you are not borrowing money |
|
Fees |
May include annual, late payment, and other fees |
No annual fee, though other fees may apply depending on your account and how you use it including overdraft fees |
|
Fraud protection |
Maximum liability of $50 for unauthorized use; dispute rights cover many problems |
Dispute rights are more limited than credit cards; delayed reporting may mean you do not get your money back |
Source [3]
Credit card uses
Credit cards can be used to make purchases in stores and online. Used responsibly over time, a credit card can help you build a good credit history, which can affect things like whether you get approved for housing, loans, and more. If you pay your balance in full each month, you can avoid interest charges entirely.
Some credit cards also offer rewards programs, allowing cardholders to earn cash back, points, or miles on their purchases. [3]
Pros of a credit card
- The opportunity to build credit.
- More security since it doesn’t draw from your checking account and you have the right to dispute a charge you didn’t make.[5]
- The ability to earn cash back and other rewards with certain cards.
Cons of a credit card
- Accrual of interest if you don’t pay your balance in full every month.
- Missed payments or high credit utilization can damage your credit and make it difficult to gain approval for credit you may need in the future.
Debit card uses
Debit cards can be used for everyday purchases, drawing directly from the money in your checking account. You are not borrowing money, and spending is limited to your available balance. [3]
Pros of a debit card
- No risk of accumulating high-interest debt, as you can only spend what is in your account.
- No interest charges, as you are spending your own money
- Easy to get, most banks issue a debit card automatically when you open a checking account, with no credit check required. [2]
Cons of a debit card
- Federal law offers stronger fraud protections for credit card users than debit card users
- Standard debit card use is not reported to credit bureaus, so it will not help build your credit
- Most debit cards do not offer the cash back or points programs that are common with credit cards [2]
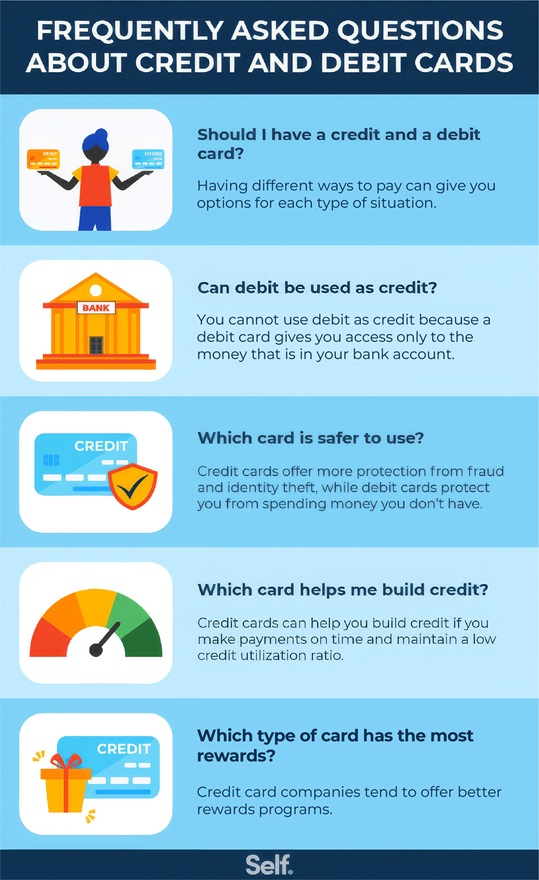
FAQs about credit and debit cards
You may have a number of questions about credit and debit cards. We’ve compiled a list of some of the most common ones and come up with some answers.
Should I have a credit and a debit card?
Having different ways to pay can be a good idea, giving you different options to fit different situations.
A credit card can be useful for larger purchases, building credit, and travel. This is especially true when you’re traveling outside the country. You could get travel-related benefits such as travel insurance, fraud protection, and the ability to avoid foreign transaction fees when making purchases abroad. [6]
Debit cards, meanwhile, are well suited to everyday purchases, as you are spending money you already have with no interest charges or balance to repay each month.
Which card is safer to use?
It depends on what you mean by safe. For protection against fraud and unauthorised charges, credit cards offer stronger legal protections; the maximum liability for unauthorised credit card use is $50, and dispute rights cover a wide range of problems. With a debit card, your liability may depend on how quickly you report the issue, and dispute rights are more limited. [2]
If avoiding debt is the priority, a debit card is the safer choice. You can only spend what is in your account, and there are no interest charges or monthly bills to manage. [2] You may have to pay fees if you spend more than what’s in your account.
Which card helps me build credit?
Traditionally only credit cards can help you build credit directly. Debit card use isn’t reported to the credit bureaus, doesn’t go on your credit report, and does not affect your credit score.[2] Although there are specialist debit card products that are designed to help build credit.
Which type of card has the most rewards?
Credit cards generally offer better rewards programs than debit cards — most debit cards do not offer the cash back or points programs that are common with credit cards. [2]
With a rewards credit card, typically you can earn cash back, points or miles on your purchases. However, rewards cards can charge more interest than non-rewards cards, making them a relatively expensive option if you do not pay off your balance in full each month. If you do pay your balance in full, you can take advantage of rewards that you would not get with a debit card. [4]
Final thoughts
Credit and debit cards function differently and allow users different options when making purchases or accessing funds. The biggest difference involves whose money you are using: your own or a lender’s money that must be paid back. But there are other differences, too, such as the level of protection you can get from fraud, whether you will have to pay extra in interest and/or fees, and how or whether your credit is affected.
The bottom line is it’s a good idea to take all these factors into account when deciding whether and when to use a debit card or a credit card.
Sources
- MyFico. “What’s in My Fico Scores? https://www.myfico.com/credit-education/whats-in-your-credit-score. Accessed June 30th, 2026.
- Experian. "What Is a Debit Card and How Does It Work?" https://www.experian.com/blogs/ask-experian/what-is-debit-card/. Accessed June 15, 2026.
- Federal Trade Commission. "Comparing Credit, Charge, Secured Credit, Debit, or Prepaid Cards," https://consumer.ftc.gov/comparing-credit-charge-secured-credit-debit-or-prepaid-cards. Accessed June 15, 2026.
- Experian. "What Is a Rewards Credit Card?" https://www.experian.com/blogs/ask-experian/what-is-a-rewards-credit-card/. Accessed June 15, 2026.
- Experian. "What Is the Fair Credit Billing Act?" https://www.experian.com/blogs/ask-experian/what-is-the-fair-credit-billing-act/. Accessed June 15, 2026.
- Capital One. "Choosing the right credit card for international travel," https://www.capitalone.com/learn-grow/more-than-money/credit-card-for-international-travel/. Accessed June 15, 2026.
About the author
Becca has over 10 years of experience as a content writer, working across various industries including finance, digital marketing, education, travel, and technology. Her work has been featured in publications including Forbes, Business Insider, AOL, Yahoo, GOBankingRates, and more.