Back to articles
What Is the Difference Between a Charge Card and a Credit Card?
Charge cards and credit cards are similar, but not the same. Charge cards and credit cards both offer ways to purchase items based on a promise to pay later.
The main difference lies in how much you can charge and when you pay. While a charge card does not have a spending limit, and does not incur interest charges, like credit cards do, you typically must pay the full balance each month.
Key points
- Charge cards and credit cards both let you make purchases on credit, but a charge card requires you to pay your full balance each month and has no set spending limit, while a credit card lets you carry a balance over time up to a set credit limit.
- Charge cards typically require excellent credit to qualify for and often carry high annual fees, while credit cards are more widely accessible and may charge interest if you don't pay your balance in full each billing cycle.
- Both card types can affect your credit score through payment history and credit mix, but only credit cards factor into your credit utilization ratio, since charge cards don't carry a credit limit or a revolving balance.
What is a charge card?
A charge card is a form of payment that allows you to spend with no limit and no interest, but the balance typically must be paid off in full at the end of each period. Charge cards usually have steep annual fees and high penalties if the balance is not paid. [1]
Charge cards vs. credit cards
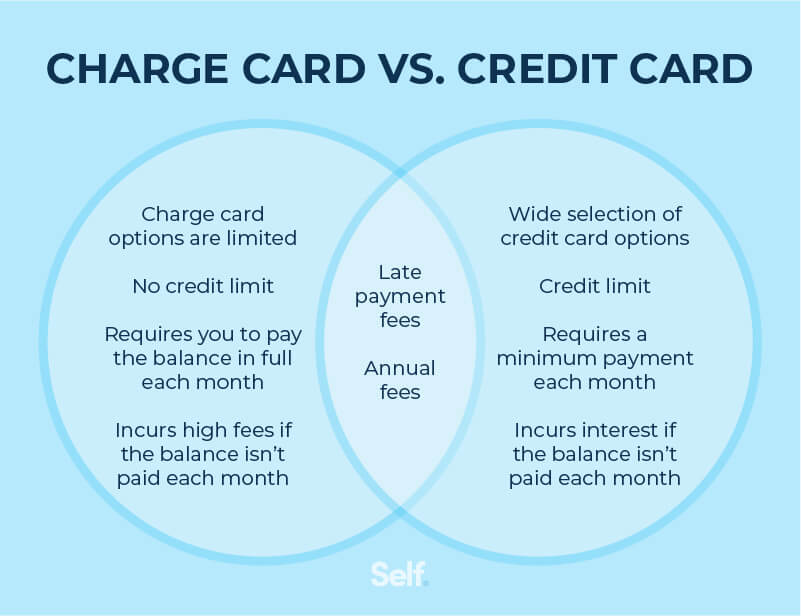
Credit cards, unlike charge cards, allow you to carry over a balance from month to month. You don’t have to pay everything off at the end of each billing cycle.
Although charge cards came first, they’re increasingly rare: Credit cards are far more numerous and popular.
There are multiple reasons for this. Credit cards are easier to obtain and give you the option of carrying a balance over from month to month. Charge cards also may come with fees, which can make them less desirable. [2]
Other key differences include the following:
Application process
Charge cards can be more difficult to get than credit cards because they’re designed for people with excellent credit. Charge card issuers need to be sure the person who’s applying can pay off the full balance by the due date every month.
Credit card applicants don’t have to do that. It’s possible to get a credit card with bad credit (although you’ll pay a high interest rate). A charge card? Not so much. [2]
Credit limit
Credit cards have a preset spending limit based on your creditworthiness, whereas charge cards generally don’t. With a charge card, your purchases are authorized based on things like your credit history and spending habits. [2]
Minimum payment
The monthly payment for a charge card is your full balance. The minimum payment for a credit card is generally a percentage of what you owe. If your minimum payment is 2% of your balance, and you’ve got a balance of $500, you’ll have to pay $10; but if your balance is $5,000, you’ll have to pay at least $100. And interest will keep accruing on whatever you don’t pay. [2]
Fees
Charge cards and credit cards both charge fees for late payments, but charge cards also carry high annual fees just to remain as a cardholder. Credit cards may or may not charge annual fees, but they’re likely to be less.
For instance, a Diners Club Elite card will cost you $300 a year. [3] Also, keep in mind that late fees are easier to avoid on credit cards than on charge cards, because you only need to make a minimum payment. [2]
Interest
Interest charges can accrue on credit cards unless you pay off your full statement balance every month. By contrast, you’re usually required to pay off the full balance on your charge card every month, so if you use it as intended, you won’t pay anything more than the cost of your purchase — except for those fees (see above). [2]
What type of card should you get?
Credit cards and charge cards each have pros and cons, which may be more or less important to you depending on your financial situation.
Pros and cons of charge cards
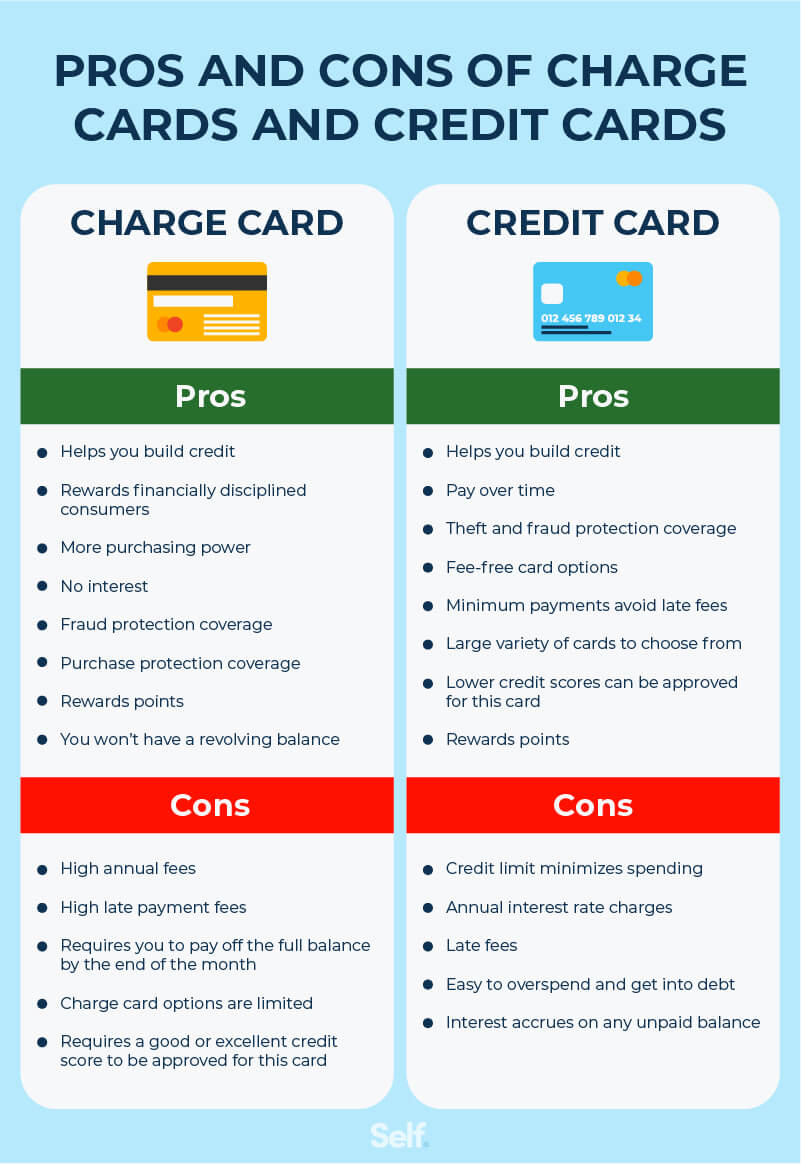
Charge cards reward and encourage responsible payment practices by requiring that you pay your balance in full every month or risk being hit with high fees. There are some advantages to this approach, but there are also drawbacks. [4]
Pros
- No spending cap – Rather than a fixed credit limit, your max spend flexes with your usage, credit history, and financial profile, useful for larger purchases without worrying about maxing out.
- No interest charges – Because balances can't roll over, you're not paying interest on what you spend. (Late fees can still bite, though, and they tend to run steeper than credit card late fees.)
- Built-in guardrail against debt – The full-balance-every-month requirement forces discipline, which can help you sidestep the kind of revolving debt spiral credit cards can lead to.
- Strong rewards – Purchase points, statement credits, and often bonus points (double or triple) on travel and dining, making them a good consideration for frequent travelers or business spenders.
Cons
- No flexibility to carry a balance – You are required pay the full amount each month; there's no minimum-payment option like a credit card offers, so a bigger single bill is unavoidable.
- Missed payments hit harder – Late or missed payments can damage your credit more severely than a late credit card payment, and skipping the full balance still triggers a late fee.
- High annual fees – Most charge cards charge a yearly membership fee, and plenty of fee-free credit and debit card alternatives exist instead.
- Fewer options to choose from – Only a limited number of issuers offer charge cards, so your choices are much narrower than in the credit card market.
Pros and cons of credit cards
Many consumers find credit cards to be a more attractive option than charge cards. But you should weigh the pros and cons before applying to a credit card issuer. [5]
Pros
- Builds your credit profile – Responsible use (on-time payments, keeping balances low) can strengthen your credit mix, lower your utilization ratio, and lengthen your credit history over time.
- Cuts down on interest with the right timing – Pay your statement in full during the grace period and you can avoid interest entirely. Some cards sweeten this further with 0% intro APR windows on purchases or balance transfers.
- Earns you something back – Cash back, points, or airline miles accumulate with everyday spending. The richest rewards programs tend to carry annual fees, so they may only pay off if you clear the balance monthly.
- Smooths out travel – Lounge access, free checked bags, rental car coverage, and simpler hotel bookings (no preauthorization holds like debit cards).
- Backs you up as a consumer – Extended warranties, the ability to dispute bad or fraudulent charges, and capped (often zero) liability if the card is lost or stolen.
- Simplifies tracking – Statements and card apps can give you a built-in record of spending, with alerts you can customize.
- Beats carrying cash – Accepted almost everywhere, lets you spend up to your limit, and gives you the option to pay over time if needed.
Cons
- Can spiral into debt – Overspending plus minimum payments can trap you in a cycle where interest outpaces what you're able to pay down, forcing you to borrow further just to keep up.
- Carries steep interest – Balances left unpaid can rack up 20%+ APR depending on the card. Rates are usually variable too, so they shift with the federal funds rate — and a 0% intro rate jumps to the standard rate once the promo period ends.
- Tempts overspending – Spending on plastic can be easier to lose track of than cash, and access up to your full credit limit can encourage charges you wouldn't otherwise make.
- Loaded with potential fees – Annual fees, authorized-user fees, cash advance fees, and late fees (which can also trigger a penalty APR) can all chip away at any value the card provides.
- Can hurt your credit – Opening an account may add a hard inquiry and shortens your average account age; missing a payment by 30+ days or running a high balance relative to your limit can drag your score down meaningfully.
How do charge cards and credit cards impact my credit?
A charge card can help you build and maintain a good credit score by encouraging you to make on-time payments, which become part of your credit history and boost your FICO® score. (Payment history is the biggest single factor in determining your FICO® score).
The second biggest factor is your credit utilization ratio, or CUR: your total outstanding balance divided by your credit limit. But charge cards don’t have a credit limit, and since you’ll be paying your balance in full every month, your CUR won’t be affected. There won’t be any credit utilization for credit bureaus to put on your credit report.
Credit cards can help you build credit, too. They can increase your credit mix, which counts for 10% of your credit score under the FICO® system (one of two main scoring models). If you’ve got other kinds of credit on your record, such as a car loan and student loans, adding a credit card and keeping up with payments can help.
If you don’t have much credit history or are seeking to rebuild your credit, a secured credit card can help. You secure your card by depositing a few hundred dollars into a linked account that isn’t touched as long as you make your payments on time, which will help you improve your credit score.
Adding another credit card may help your credit utilization ratio if you make only nominal charges on that card, because you’ll be adding to your overall credit limit without significantly changing your level of debt.
However, opening a new credit card may not increase your credit right away. The age of your credit accounts is a factor in determining your credit score and every time you apply for credit, it counts as a hard inquiry, which can shave a few points off your score. [6]
Moving forward
Credit cards and charge cards each have advantages and disadvantages. Together or separately, they can provide you with payment options and they can give you greater protection than a debit card.
Knowing the difference between the two is important in deciding what kind of role you want each to play in your life. You’ll want to consider a number of factors, from your spending habits to your financial goals, in determining whether and how to use them.
Sources
- Bankrate, “What is a Charge Card?” https://www.bankrate.com/credit-cards/advice/is-a-charge-card-same-as-credit-card/ Accessed July 28, 2026
- Equifax, “Charge Card Vs Credit Card” https://www.equifax.com/personal/education/credit-cards/articles/-/learn/charge-vs-credit-cards/ Accessed July 28, 2026
- Diners Club, “Diners Club Card Elite” https://www.dinersclubus.com/home/consumer-cards/conscards-l2/diners-club-card-elite Accessed July 28, 2026
- SoFi, “Charge Cards Pros and Cons” https://www.sofi.com/learn/content/charge-cards-pros-and-cons/ Accessed July 28, 2026
- Experian, “Pros and Cons of Credit Cards” https://www.experian.com/blogs/ask-experian/pros-cons-credit-cards/ Accessed July 28, 2026
- Experian, “How Do Charge Cards Affect Your Credit Score?” https://www.experian.com/blogs/ask-experian/how-do-charge-cards-affect-your-credit-score/ Accessed July 28, 2026
About the author
Becca has over 10 years of experience as a content writer, working across various industries including finance, digital marketing, education, travel, and technology. Her work has been featured in publications including Forbes, Business Insider, AOL, Yahoo, GOBankingRates, and more.